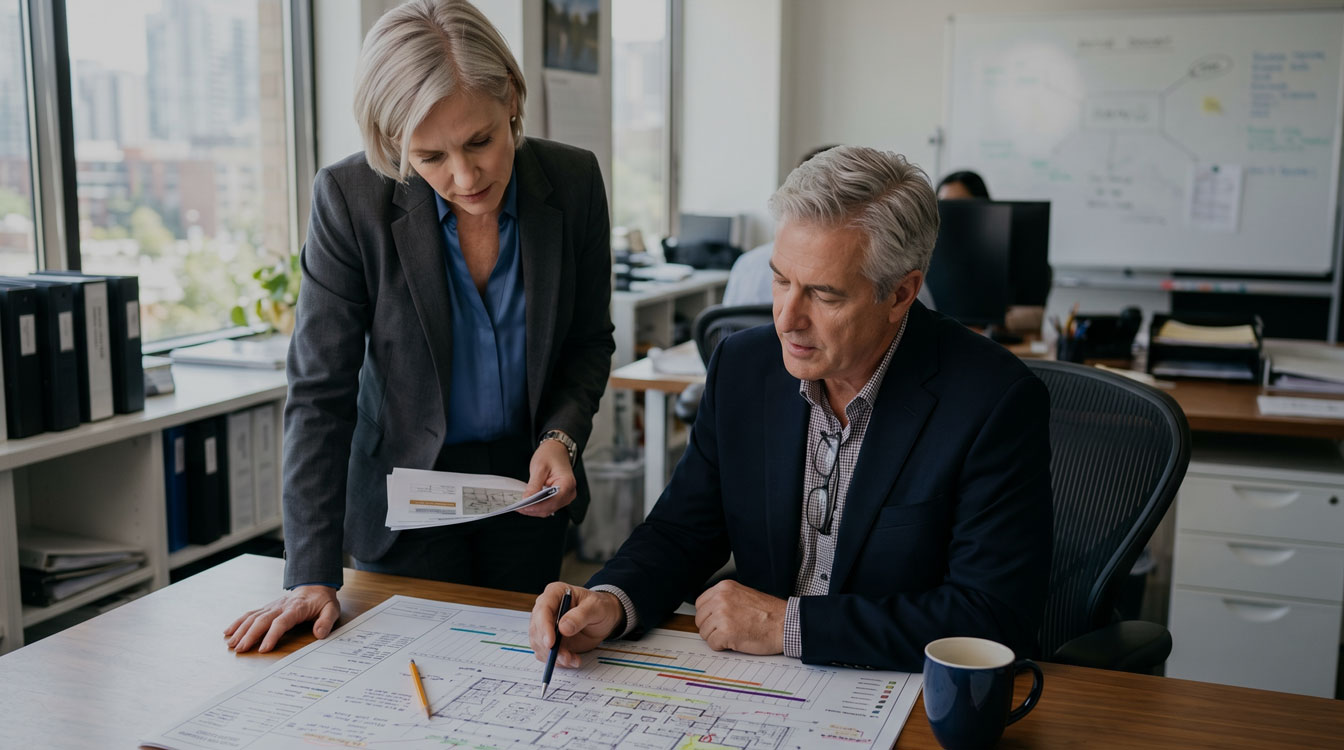
An insurance needs analysis evaluates the financial impact of potential events, such as premature death, disability or critical illness. It considers your income, debts, savings, existing insurance and financial responsibilities to identify potential gaps in protection.
The goal is to understand how much of a potential financial loss you could manage using your own resources and where insurance may help reduce the burden. Recommendations depend on your circumstances, priorities and budget.
The appropriate coverage depends on your financial responsibilities and the risks you want to address.
Life insurance can provide financial support for beneficiaries after your death, helping with expenses, outstanding debts and income replacement.
Disability insurance can replace part of your income if an illness or injury prevents you from working, subject to the policy’s terms.
Critical illness insurance may provide a lump-sum benefit following the diagnosis of a covered condition, as defined by the policy.
Long-term care insurance may help cover eligible care expenses if you need assistance with daily activities.
Workplace benefits and existing policies may already provide some protection. Reviewing them together can help identify overlapping coverage or areas that may need attention.
The amount of insurance you need depends on your financial obligations, available resources and the needs of anyone who depends on you.
An analysis may consider mortgage payments, other debts, household expenses, future education costs, income replacement needs and existing savings or benefits. Comparing these potential obligations with your available resources can help estimate a suitable level of coverage.
There is no single amount that is right for everyone. The objective is to consider protection that reflects your needs without placing unnecessary pressure on your budget.
Having insurance does not necessarily mean your current coverage remains appropriate. Your policies may no longer reflect your financial responsibilities, income or long-term plans.
An insurance review can help you understand policy benefits, premiums, exclusions and limitations, as well as how workplace coverage fits with personal policies. Before replacing or cancelling an existing policy, consider whether new coverage is available and appropriate, since approval and costs may depend on factors such as age and health.
Consider reviewing your insurance when you experience a significant life change, such as getting married, starting a family, buying a home, changing careers, starting a business or approaching retirement. Changes in debt, income or family responsibilities may also affect your coverage needs.
Regular reviews can help keep your insurance strategy aligned with your financial plan as your circumstances evolve.
Insurance analysis is an important part of financial planning because it helps you understand potential risks and make informed decisions about financial protection.