Your paycheque comes in, rent is due, groceries cost more than expected, and somehow you’re supposed to save for the future, too. Sound familiar?
When you’re starting out, figuring out what to do with your money can feel overwhelming. Should you pay off student loans, build up savings, start investing or work toward buying your first home? With so many competing priorities, knowing where to begin isn’t always easy.
The good news is that you don’t need to have it all figured out. Small, practical steps today can help you build good financial habits, handle unexpected expenses and create more options for the future.
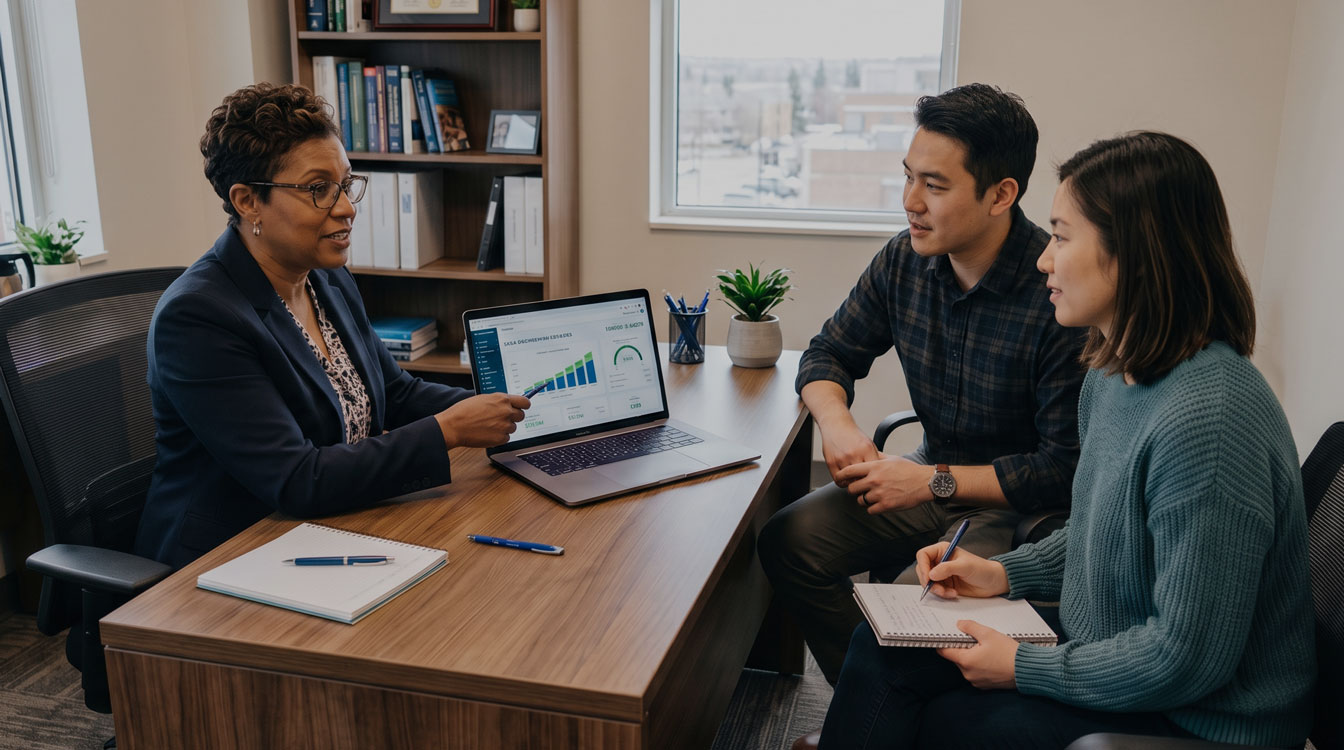
Start by understanding your income, expenses, debts, savings and financial priorities. Knowing where your money goes can help you identify opportunities to save and decide which goals deserve attention first
You do not need to have substantial assets or a complicated financial situation to benefit from planning. Establishing good financial habits early can provide a foundation for future decisions.
A budget helps you understand how much money comes in, where it goes and what you can reasonably set aside for future needs. Tracking regular expenses can reveal spending patterns and help you balance everyday costs with longer-term goals.
Consider building an emergency fund for unexpected expenses, such as car repairs or a temporary loss of income. The amount you need will depend on your circumstances, but setting aside money consistently can help reduce reliance on credit when surprises arise.
The right approach depends on the type of debt you have, its interest rate, your essential expenses and your available savings.
High-interest debt can become expensive over time, so paying it down may be a priority. At the same time, maintaining some accessible savings can help you manage unexpected costs without taking on additional debt.
A balanced plan can help you decide how to divide available money between debt repayment, emergency savings and other financial goals.
Investing may help you work toward longer-term goals, but it is important to understand your financial needs and the risks involved before getting started. Money you may need soon is generally better suited to accessible, lower-risk savings options than investments that can fluctuate significantly in value.
Before investing, consider your time horizon, comfort with risk, existing debts and emergency savings. An investment strategy should reflect your individual circumstances rather than short-term market trends.
Canadian residents may have access to registered accounts designed for different purposes.
Tax-Free Savings Account (TFSA): Investment growth and qualifying withdrawals are generally tax-free, subject to applicable rules.
Registered Retirement Savings Plan (RRSP): Eligible contributions may be tax-deductible, while withdrawals are generally taxable.
First Home Savings Account (FHSA): Eligible contributions may be deductible, and qualifying withdrawals to purchase a first home can be tax-free.
Each account has specific eligibility requirements and contribution rules. Choosing the appropriate option depends on your goals, income and financial circumstances.
As your income, family circumstances and priorities evolve, your financial strategy can be reviewed and adjusted to remain relevant.
Many people will offer you advice on which investments to buy. But there’s more to your financial life than your RRSP. Estate taxes, income taxes and education funds for your children are just…
Using an Independent Mortgage Broker can SAVE you thousands of dollars in interest payments. And that’s MONEY you can use for other things. Whether you are a first time home buyer, looking to…
Term life insurance is the most basic of life insurance products in that it has no savings component, and thus no cash value. By the name, it is purchased for a ‘term.’ One of the most common uses of…
The TFSA is a registered savings account that allows taxpayers to earn investment income tax-free inside the account. Contributions to the account are not deductible for tax purposes, and…
Everyone who enjoys good health hopes it will last for a lifetime. But it doesn’t always turn out that way. Sometimes life throws a curve. Injuries can happen. A disability illness could dramatically…
RESPs are registered education savings plans that grow tax-free until the child is ready for university, college or a vocational institute. The student usually pays little or no tax on those funds when they are…
A critical illness can happen to anyone. And it does happen to many. Canadians are more likely to experience a critical illness than they are to die before the age of 75. For most people, the…
A will is a written document, properly signed, which: (1) specifies who is to administer the estate (the executor), (2) specifies what is to happen with the assets and liabilities of the estate…